Finding water where it doesn't belong is stressful enough. Then a second worry sets in almost immediately: will your insurance actually pay for this? It's one of the first questions we hear from homeowners across Buena Park and North Orange County, usually while they're still standing in a wet hallway with towels in hand.
Here's the short version. Most standard California homeowners policies cover water damage that is sudden and accidental — a pipe that lets go overnight, a supply line that fails behind the washer, a water heater that splits at the seam. What they typically do not cover is flooding from outside the home and damage that crept up slowly from a leak you could have caught. The exact rules, of course, live in your own policy.
This 2026 guide walks through what is usually covered, what usually isn't, and how to give your claim the strongest possible footing. Treat it as general information for California homeowners, not legal or policy advice. Always read your declarations page and call your agent to confirm your specific coverage.
The Key Test: Was the Damage Sudden and Accidental?
Almost every coverage decision comes down to one distinction: was the damage sudden and accidental, or gradual and preventable? Insurers cover the first and exclude the second. A pipe that bursts at 2 a.m. and floods your kitchen is the classic covered event. A supply line under the sink that has been dripping for eight months, quietly rotting the cabinet base, usually is not.
The reasoning is that homeowners are expected to maintain their property. A slow leak leaves signs — a musty smell, a warped baseboard, a rising water bill — and the policy assumes you had a chance to act. A sudden failure gives you no such warning, which is exactly what insurance is meant to protect against.
This is why the cause of the loss matters more than the mess itself. Two homes can have identical water on the floor, and one claim gets paid while the other is denied. If a fitting suddenly fails, our burst pipe cleanup crew documents the failure point so the sudden-and-accidental nature of the loss is clear to your adjuster.
What Homeowners Insurance Usually Covers
Under a typical California HO-3 policy, the following causes are generally covered when they happen suddenly:
- Burst, frozen, or ruptured plumbing pipes inside the home
- Sudden appliance failures — a washing machine hose that splits, a dishwasher that overflows
- A water heater that ruptures without warning
- Accidental overflow from a tub, sink, or toilet
- Roof leaks caused by a covered peril, such as wind or hail that tears off shingles
- Damage from putting out a fire, or from a burst sprinkler line
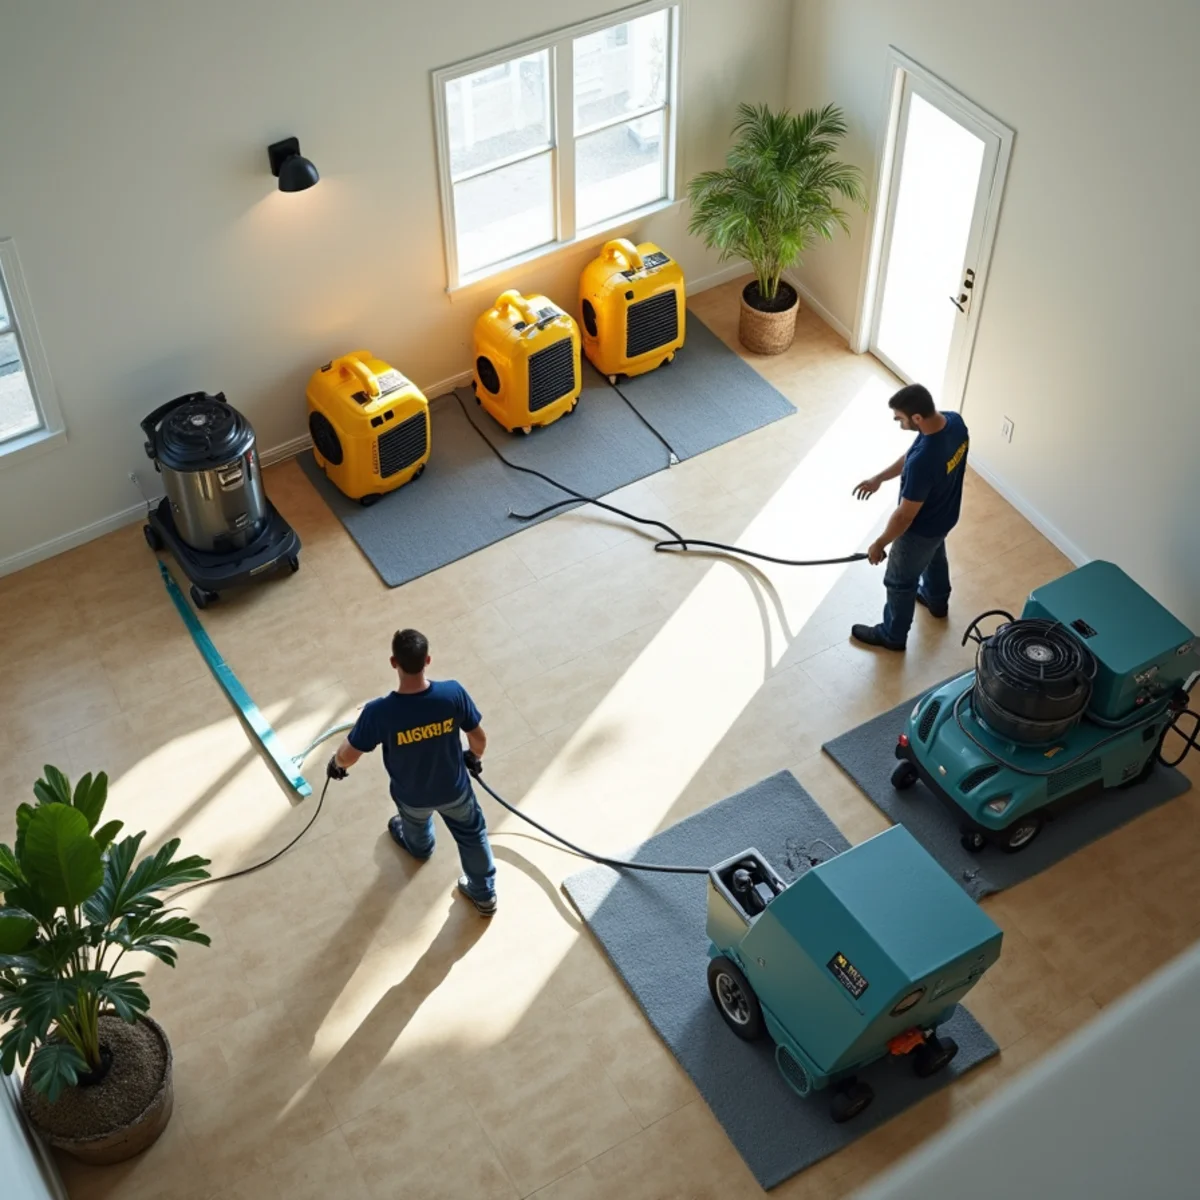
When the cause is covered, the policy generally pays to dry the structure, tear out unsalvageable materials, and repair the damaged areas — minus your deductible. That's the mitigation and rebuild side that a full water damage restoration project handles, from extraction through reconstruction.
What's Usually Not Covered
The exclusions trip up more homeowners than anything else. These are the situations standard policies commonly leave out:
- Flooding from outside — rising creeks, storm surge, or heavy rain pooling against the foundation
- Gradual leaks and long-term seepage that developed over weeks or months
- Damage traced back to deferred maintenance or neglect
- Sewer or drain backups, unless you added an endorsement (more on that below)
- Mold, when it grew because a known leak went unaddressed
- The cost of fixing the source itself — the broken pipe or failed appliance
That last point surprises people. A policy will often pay to repair the wall and flooring the water ruined, but not to replace the corroded pipe that caused it. The damage is covered; the failed part usually isn't. Knowing that distinction ahead of time keeps expectations realistic when the estimate arrives.
Floods Are a Separate Policy — and It Matters Near Coyote Creek
This is the single biggest gap California homeowners overlook. Standard homeowners insurance excludes flood damage entirely. Coverage for rising water comes only from a separate flood policy, whether through the National Flood Insurance Program or a private flood insurer.
In our area that isn't hypothetical. Coyote Creek runs along the northwest edge of Buena Park where it meets Cerritos and La Mirada, and the winter storm season from November through March can push water past its banks. If your home sits near the creek in Buena Park, or just over the line in Cerritos or La Mirada, a flood policy is worth pricing out. Flood policies also carry a waiting period before they take effect, so buying one the week rain is forecast won't help.
Sewer Backups and Sump Overflows: Check for an Endorsement
When a sewer line or floor drain backs up into the home, standard policies usually treat it as excluded. Many insurers offer a water or sewer backup endorsement — an optional add-on, often for a modest annual premium — that fills this gap. If you have a lower-level bathroom, a basement, or a home on older sewer lines, it's worth asking about.
This matters for health reasons, not just money. Sewage backups are category 3 water, meaning grossly contaminated, and they call for specialized handling. Our sewage cleanup process follows strict containment and sanitizing steps that a standard mop-and-dry cannot match, and the endorsement is often what makes that work affordable.
Your Deductible and How the Payout Works
Even on a fully covered claim, you pay your deductible first. On a smaller loss, the repair cost may land close to the deductible, and it's worth weighing whether filing makes sense at all — multiple small claims can affect your future premiums.
Pay attention to whether your policy pays actual cash value or replacement cost. Actual cash value subtracts depreciation, so a ten-year-old floor is reimbursed as a ten-year-old floor. Replacement cost coverage pays to restore materials to like-new condition, usually in two stages, with the depreciated portion released once repairs are complete. Keep every receipt and estimate, because that paper trail is what unlocks the second payment.
How to Give Your Claim the Best Shot
A few habits make the difference between a smooth claim and a frustrating one:
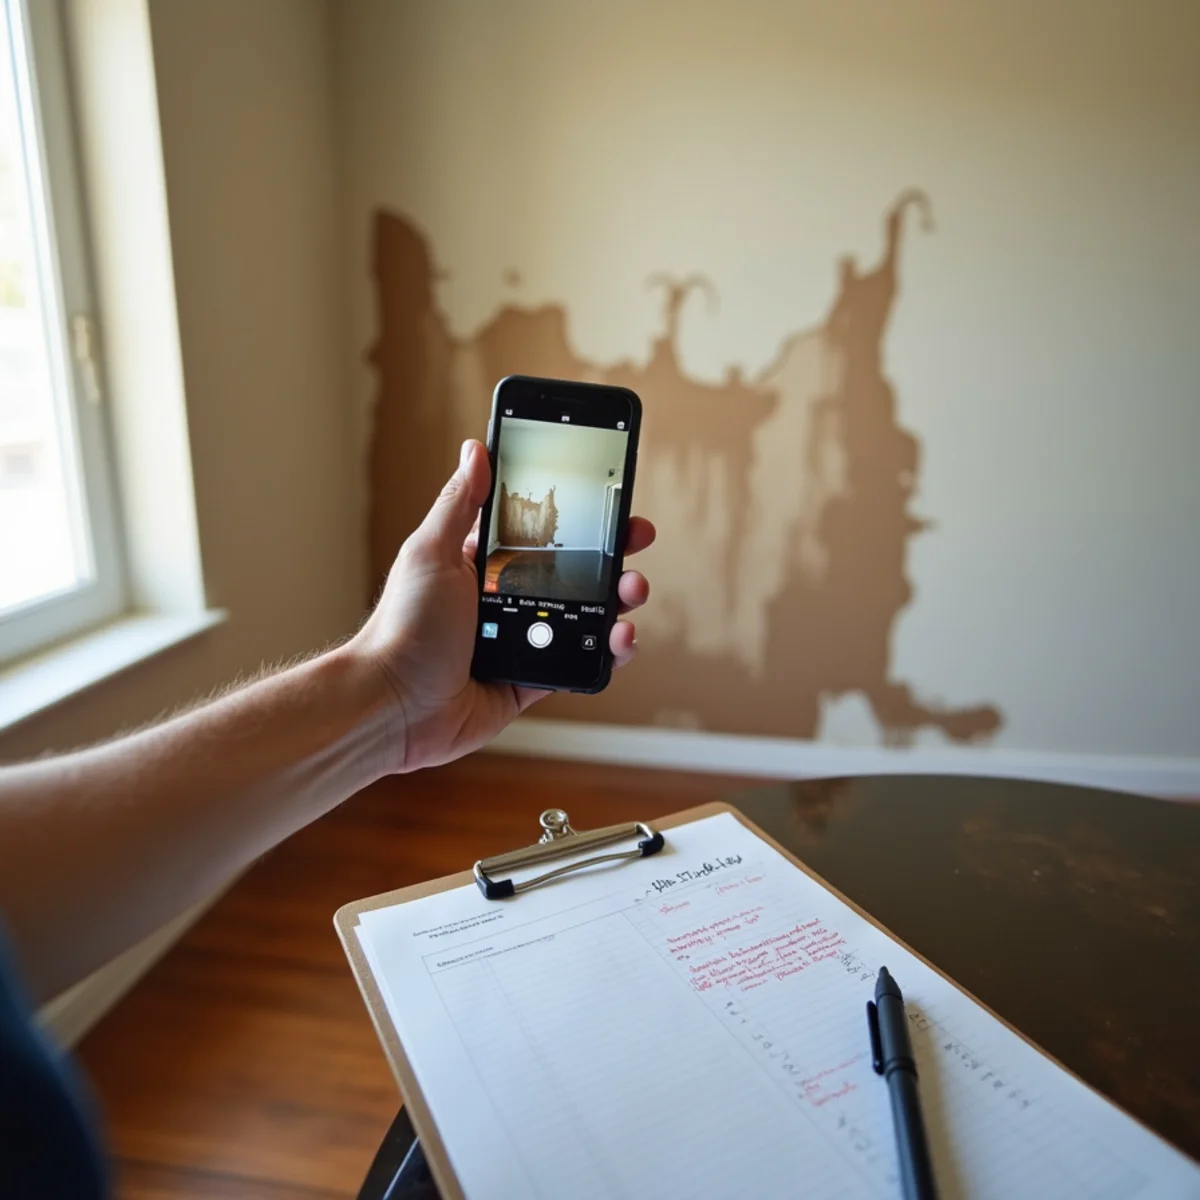
- Stop the water and photograph everything before you clean up
- Call your insurer promptly to report the loss and start a claim number
- Save damaged items and receipts rather than tossing them
- Get a professional moisture assessment so the true scope is documented
We do this work every day, and we bill your insurer directly whenever your policy allows it. Our insurance claims help means you're not translating adjuster jargon alone, and our free inspection gives you a documented scope of the damage before any decisions are made. That combination tends to move claims along faster and with fewer surprises.
Frequently Asked Questions
Usually yes. A pipe that bursts suddenly is the textbook example of sudden and accidental damage, and most standard California policies cover the resulting cleanup and repairs. Coverage typically pays to fix the damaged walls and floors but not to replace the pipe itself, and your deductible still applies.
The most common reasons are that the damage came from an excluded cause — outside flooding or a sewer backup without an endorsement — or that it built up gradually from a leak that went unaddressed. Denials also happen when documentation is thin, which is why photos and a professional moisture report matter so much.
It depends. If mold grows as a direct result of a covered sudden loss and you acted quickly, it may be covered, though many policies cap mold remediation. If mold traces back to a slow, neglected leak, it's usually excluded. Fast drying is the best way to keep mold out of the picture entirely.
Yes, if you want protection from rising water. Homeowners policies exclude flood damage, so coverage for creeks, storm surge, or rain pooling against the foundation comes only from a separate flood policy. Homes near Coyote Creek in Buena Park and neighboring cities should give this serious thought before winter.
Dealing with water damage right now?
Water Damage Buena Park responds 24/7 across Buena Park & North OC.